Roof Insurance Claims · Sugar Land, TX
Free inspection, thorough documentation, and we meet your adjuster on site — with particular attention to HOA rules and the approved scope.
Insurance Claims
Most roof claims are not won or lost at the adjuster meeting. They are decided by how well the damage was documented before it. An adjuster is on a schedule and looking at a lot of roofs; if nobody has laid out the damage clearly, the easy answer is wear and tear.
Sugar Land carriers see a lot of hail and wind claims across First Colony, Telfair, Riverstone and New Territory, and HOA architectural rules can affect which shingle the approved scope actually needs to cover. We factor that in before the adjuster ever shows up.
Building Edge Construction inspects the roof for free, photographs every finding, and meets your adjuster on site so the same evidence is in front of both of you. If the approved scope comes back missing damage that is clearly there, we document it and submit a supplement. Owner John Baudry has been doing this side of the business for years.
Request a Free Inspection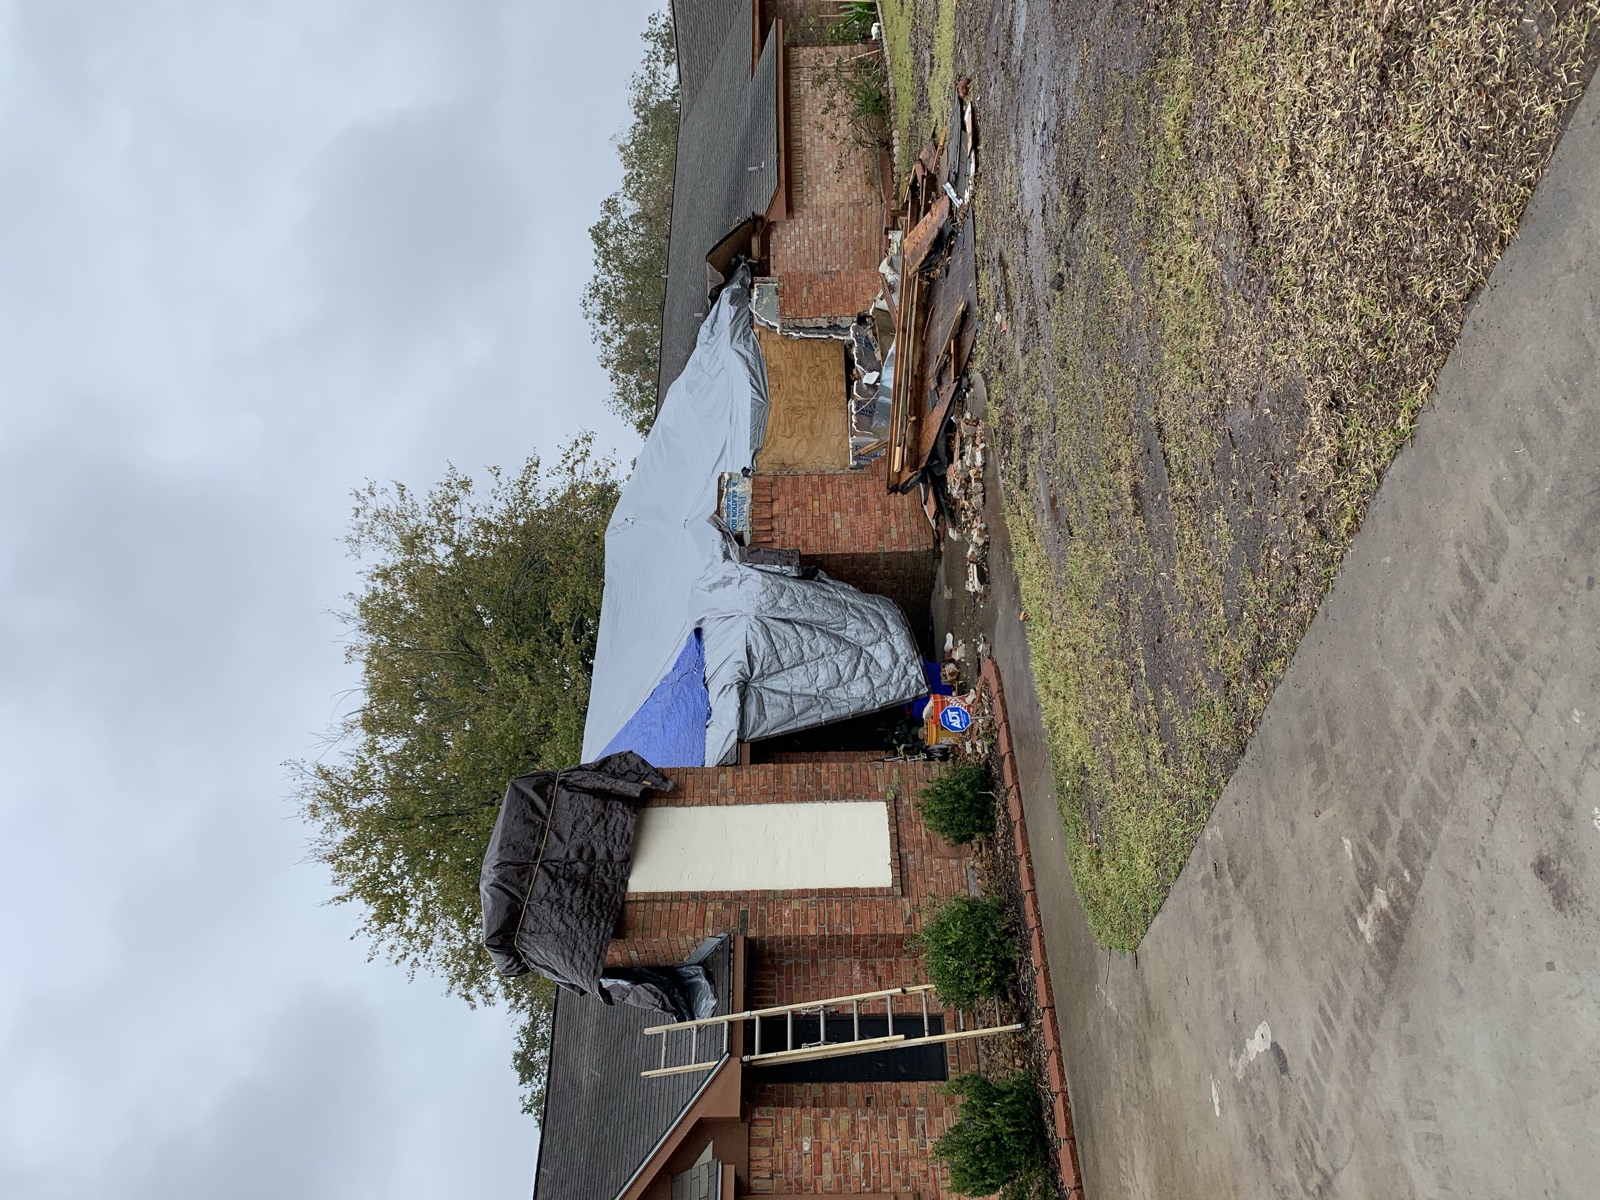
Know the Signs
A specific storm, hail or wind event you can point to a date for
Dented gutters, vents, flashing or garage door after that storm
Missing, lifted, cracked or bruised shingles
An active leak or new interior water staining
Neighbors on your street who have had claims approved
A prior claim that was approved but never fully completed
Not sure you have a claim? We will tell you honestly if you do not. Free Sugar Land inspection.
Sugar Land Specifics
The most common problem we see in Sugar Land is a scope that technically covers a roof replacement but not the shingle your HOA will approve. If the adjuster writes for a builder-grade three-tab and your community requires an architectural shingle, that gap lands on you unless somebody catches it up front. We check the HOA guidelines during the inspection and raise it while the scope is still being written, not after the check arrives.
How It Works
Documented with photos before anyone files anything.
You open the claim with your carrier — we give you the evidence.
We meet them on the roof and walk the damage together.
We complete the covered repairs and close it out with you.
Know the difference
Your adjuster works for the insurance company and decides coverage. Building Edge Construction is your contractor — we inspect, document and perform the work. We are not a public adjuster and we do not legally represent you in the claim, but having someone who knows roofs standing on the roof with the adjuster changes the conversation.
By City
Common Questions
Only if you actually have storm damage. Filing on a roof that is simply old rarely ends well. Get a free inspection first — we will tell you plainly whether the damage is claimable, and we will tell you when it is not.
It can. If your community requires a specific shingle type or color and the approved scope was written for a cheaper material, the difference can come out of your pocket. We review the HOA requirements during the inspection and flag any mismatch before the scope is finalized.
It happens often, and it is not necessarily the end of it. If the approved scope misses damage that is clearly documented, we can submit a supplement to your carrier with the photos and measurements behind it.
Yes, and we strongly recommend it. We walk the roof with your adjuster so the damage we documented is being looked at directly rather than described second-hand.
On a covered claim it is usually just your deductible. The inspection is free, and we go over the numbers with you in writing before any work starts.
No. We are your contractor. We document damage and perform the repairs, and we work directly with your insurance company — but coverage decisions are made by your insurer, and we do not legally represent policyholders in a claim.
Get Started
24/7 emergency disaster response. If life safety is involved, call 911 first.